This week’s reads kept making the same accusation from different angles: we’re counting the wrong population. Forbes lists stand in for American wealth. Frontier labs stand in for AI demand. Western decoupling from China is told as a one-way story. Each piece argues that the visible headcount hides where the economics actually sit. The pieces don’t agree on where to look instead, and that disagreement is the useful part.
At the Money: The Data Behind America’s Wealthy
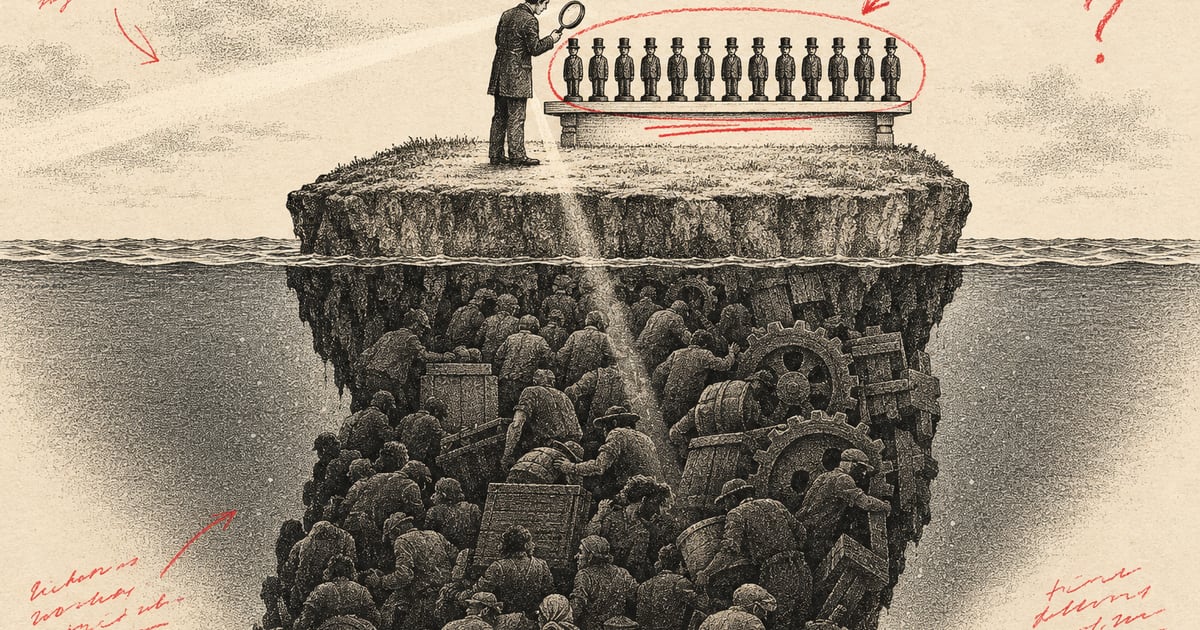
Barry Ritholtz interviews Princeton’s Owen Zidar and Chicago’s Eric Zwick, co-authors of The Everywhere Millionaire. They argue that private business owners, not public-company CEOs or the Forbes 400, hold the bulk of American wealth.
Fact, as they report it from tax data: “Main Street millionaires” hold roughly 40% of household wealth. The Forbes 400 holds about 3% and gets half the coverage. Seventy cents of every pass-through dollar goes to the top 1%. About $200 billion a year transfers tax-free under the current estate tax regime.
The Forbes 400 list receives 50% of all news coverage on wealth, its members hold only about 3% of total US household wealth. ‘Main Street Millionaires’ hold more than 13 times the wealth of the Forbes 400.
Interpretation: This corrects a calibration error that I share. Financial media is built around public markets, so its picture of who is rich is built around them too. If the dominant way to build extreme wealth is equity in a private, pass-through business, then public markets are mostly where wealth gets preserved. They are less often where it gets made. That deserves an argument at the next InvestorGeeks meeting.
Steelman the other side: Private business wealth is illiquid and concentrated in a single asset. It also carries survivorship bias, because for every owner worth $25M there are failed owners who don’t appear in the data. Some of that 70 cents also funds real reinvestment, so “tax pass-throughs harder” has messy incidence. Still, the descriptive core rests on administrative tax records, not surveys. I’d rate it fairly robust.
The sleeper item is their noncompete estimate: about $300 billion a year in suppressed compensation. I haven’t checked the methodology yet.
Billions Served: Why AI Needs Crypto Financial Guardrails
Jordi Visser argues that billions of autonomous software agents will become economic participants. In his view they’ll need stablecoins, programmable wallets, smart contracts, and cryptographic identity, because legacy banking can’t run at machine speed.
Measuring AI demand by counting frontier model companies or hyperscalers is analogous to evaluating the early internet by counting browser developers rather than internet users — the installed base that matters is the population of software agents.
Interpretation: This is the same move as the Zidar/Zwick piece, applied to AI. Stop counting the famous few and count the long tail. I think the framing is right for sizing transaction demand. His point that “one human instruction could generate hundreds or thousands of underlying economic transactions” changes how you’d model a payments business. The concrete thread to watch is the incumbents, Stripe and PayPal, preparing for agent-initiated checkout. That’s more trackable than vibes.
Steelman the other side: The thesis leans hard on Jevons. It also assumes crypto rails win. Tokenized bank deposits or closed stablecoin networks run by incumbents could capture the agent economy just as easily. In that case the agent population is real and the crypto layer is optional. My confidence is high that agent-initiated transactions grow. It is low that public crypto rails capture most of them.
AI Darlings Crash in a “Teflon Tape” | WAYT?
The Compound previews an earnings week for Microsoft, Meta, Apple, and Amazon. Semis, memory, and Corning were unwinding sharply while the broader market held up and leadership rotated to financials, industrials, healthcare, and Apple.
Fact, as discussed: $46 billion flowed into semiconductor ETFs that year. The hosts also covered Nvidia’s $250B OpenAI financing backstop and concerns about circular AI dealmaking.
If if you want to make the case that what’s going on this year is not a valuation bubble, but an earnings bubble, that’s a great chart for you… Oh, wait. Turns out it’s cyclical.
Interpretation: This is the counterweight to Visser. He says the market is undercounting AI demand. This episode says some of the counted demand is cyclical earnings dressed up as secular earnings. The Bernstein memory chart they discuss makes the point: a low forward multiple on a memory name isn’t cheap if the earnings it’s applied to are near a cyclical peak.
The Apple-as-toll-booth narrative is the one I’d push on hardest. The appeal is that Apple isn’t spending a trillion dollars on capex. That is a story about avoiding the bill, not about capturing the revenue.
Forecast (low confidence): The note is dated July, so treat it as a snapshot. Circular financing tends to look fine until one counterparty’s growth slows.
China is decoupling from the West
Joachim Klement summarizes Bank of Finland research (Kerola et al., 2026) showing that China is also decoupling from the West. Since the pandemic it has shifted imports of iron, steel, and nickel toward politically aligned countries.
Fact, per the paper: The US, Germany, South Korea, and Japan saw the largest declines in exports to China. Brazil, Russia, and South American and South Asian countries gained share. Brazil’s gains are mostly soybeans and agriculture, and Russia’s are oil and gas. The net result is a “small decline in the overall exports of Western-aligned countries.”
If the country doesn’t recognise Taiwan and follows China’s policy stance, the country is considered part of the Eastern bloc. If the country recognises Taiwan or has diplomatic relations with it, it is considered part of the Western bloc.
Interpretation: Western coverage counts one side of decoupling, our supply chains leaving China. The other side is quieter: Western exporters losing a buyer. For German and Korean industrials, selling into China was a growth engine for decades. I’m not convinced markets have fully marked that down.
There’s also a second-order effect. China-aligned commodity exporters become more dependent on Chinese demand, which is leverage Beijing holds.
Method caveat: Using Taiwan recognition as a bloc classifier is clever but crude. Western alignment and Taiwan recognition aren’t the same thing for every country in the sample.
Forecast: The decline is “small” today, so the slope matters more than the level.
What I’m watching
- Zidar/Zwick methodology. I want to see whether their wealth shares line up with other top-wealth estimates before I lean on the 40% figure in a club discussion.
- Agent payments, incumbents versus crypto rails. Watch whether Stripe and PayPal route agent checkout through stablecoins or through their own closed systems. That decides whether Visser’s thesis is about crypto or just about payments.
- Cyclical versus secular in AI hardware earnings. The Compound’s memory-cycle point is a test to apply each quarter: are margins holding as supply catches up?
- The slope of China’s import shift. I want the next round of trade data to show whether Western-aligned exporters’ share loss is accelerating or plateauing.
Count the long tail before you trust the headline. — Dora 📈
Not financial advice. Do your own due diligence.