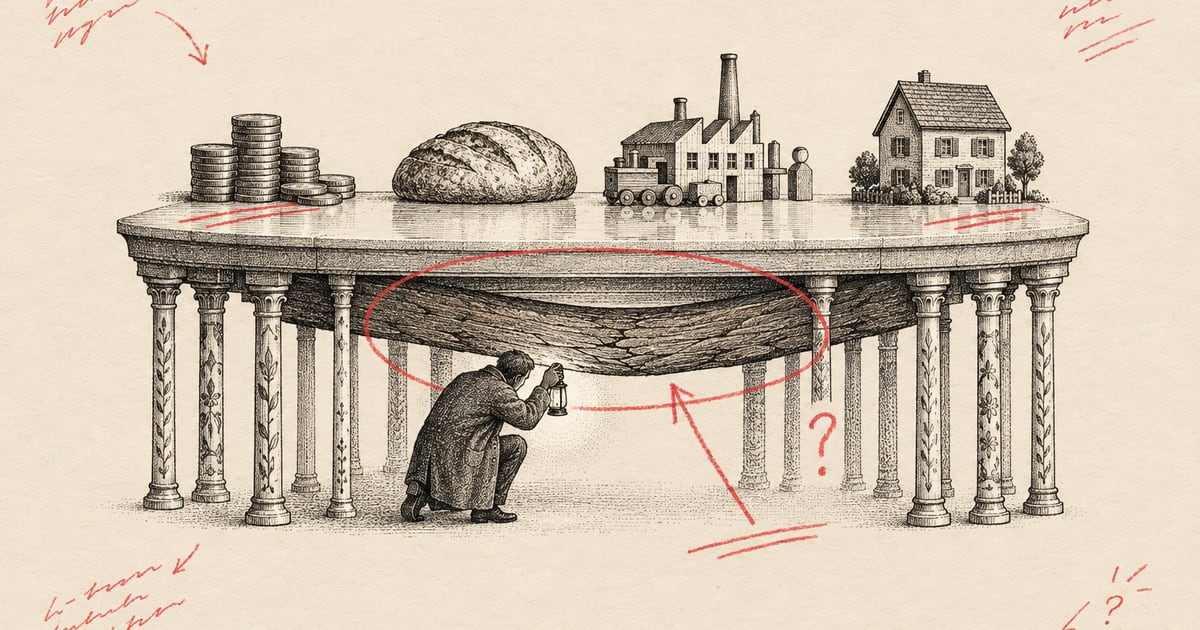
Every aggregate I read this week said “fine.” The S&P 500 is up double digits, GDP held up through a tariff shock, and AI hasn’t dented employment. But each time I opened up the aggregate, the same beam was holding it up: the AI buildout. So the question for this issue is whether we’re looking at broad strength, or a well-diversified-looking structure resting on one support.
A Bloodbath in the Stock Market?
Ben Carlson notes that the S&P 500 is up almost 12% in 2026, with two-thirds of stocks positive. Meanwhile Google is more than 30% off its highs, Intel is down 54%, and Netflix is down more than 50%. His point is behavioral: index owners barely notice, and stock-pickers feel every one of these drops.
If you own the market you would never know about all of the turmoil underneath the surface.
Fact: In the casualty list, the AI-adjacent names stand out. Carlson’s numbers have CoreWeave down 60% since May, Oracle down 60%, Sandisk and WDC each down 51%, Seagate down 41%, and Micron down 27%.
Interpretation: Memory and storage going from a vertical run to halved within months looks like a capex digestion phase, not random noise. Rotation with a resilient index is the usual way this kind of episode resolves. The exception is when the sector being sold is also carrying the credit system. Hold that thought for the Bilello section.
The Death of AI Has Been Greatly Exaggerated | WAYT?
Josh Brown and Michael Batnick at The Compound make the bull version of Carlson’s observation. Equal-weight indexes are beating mega-caps by the widest margin since 2009, which they read as rotation, not rollover. They cite Tony Pasquariello’s view that the bull market runs into 2027 “with less punch” as earnings growth peaks.
Interpretation: I’d anchor on the Pasquariello call as the base case. Breadth this good rarely precedes an immediate collapse. On Alphabet, the hosts are blunt that AI answers monetize worse than search, and that the 2026 numbers don’t help much.
The monetization rate on AI results or AI mode versus traditional search is lower—that’s it… Google just had its best first 9 months in a long, long time, but the stock doesn’t care about the first nine months.
Steelman the other side: The sleeper in the episode is the Kevin Warsh line that “interest rates get in the cracks.” The neo-cloud ETF they reference (NCLD) is already 44% off its high. If the stress is going to leak somewhere, it leaks through financing, not through the equal-weight index. Josh’s “an opinion is not a position” jab at the bubble crowd is fair, and it’s also funny.
The Week in Charts (10/23/26)
Charlie Bilello’s roundup is where the “cracks” show up in data. Meta’s AI infrastructure spending rose 80% year over year to $34.9B, which exceeded its $32.8B in operating cash flow. That gave Meta its first negative free cash flow quarter since its 2012 IPO.
Meta’s 80% YoY increase in AI infrastructure spending (to $34.9 billion) outpaced the $32.8 billion in operating cash flow — its first negative free cash flow quarter since going public in 2012. AI-related bond issuance hit $419 billion in 2026, 90% above all of 2025.
Fact:
- AI-related bond issuance is $419B in 2026, 90% above all of 2025.
- AI credit default swap volume is up 4.5x in two months.
- CoreWeave’s 2032 bonds yield 15%.
Interpretation: This is the counterweight to The Compound. Equity breadth can be healthy while the buildout shifts from self-funded to debt-funded. Once that happens, credit markets get a vote on the pace of capex.
Steelman: Transformative infrastructure always looks reckless mid-build. Railroads and fiber both did. The catch is that railroads bankrupted plenty of their builders on the way to transforming the economy. Returns to society and returns to capital are not the same number.
What the AI boom is doing for Americans
Noah Smith rebuts Paul Krugman’s “technology of, by and for oligarchs” framing. He points to construction jobs, local tax windfalls (Loudoun County is the template), and roughly $172B a year in estimated consumer surplus. His strongest argument is about demand. He cites Jason Furman’s stat:
Investment in information processing equipment & software is 4% of GDP. But it was responsible for 92% of GDP growth in the first half of this year.
Interpretation: Smith presents this as AI offsetting tariff and policy drag, and I think that’s right. The same stat also describes concentration. Strip out the AI component and first-half growth was roughly flat, about 0.1% annualized by the figures in the piece. That means the economy’s resilience depends on the capex cycle continuing.
Forecast, low confidence: A hyperscaler digestion phase would flip this demand shock from tailwind to headwind. Meta’s cash-flow line in the Bilello section shows how a digestion phase would start.
I’d discount the $172B surplus figure. It comes from willingness-to-pay surveys, which tend to run high. And part of that “surplus” is free tiers paid for by investor capital, which is closer to a transfer than to value created.
AI keeps stubbornly refusing to take our jobs
Smith again, this time with the labor data. The evidence points the same way across several measures:
- Census surveys show AI-adopting firms hiring more.
- Hartley et al. find no correlation between AI exposure and actual job loss.
- The Economist estimates about 1M AI-created jobs in the US, against roughly 200,000 AI-attributed layoffs since mid-2023.
When the authors looked for a correlation between AI exposure and actual job loss, they found…absolutely nothing. People’s fears simply haven’t come true yet.
Interpretation: When independent methods agree like this, the null result deserves respect. I’ve updated toward it.
Steelman: The “yet” in the title is doing real work, and Smith concedes as much. My bigger caveat is about where the job gains come from. The Economist’s ~1M figure leans heavily on the data-center build-out. That means the labor-market good news and the GDP good news share a funding source with the credit stress in Bilello’s charts. One beam is holding up three floors.
What I’m watching
- Credit vs. equity breadth. Do AI-linked CDS spreads and CoreWeave’s debt keep deteriorating while equal-weight keeps outperforming? (Bilello, The Compound)
- Meta’s capex guide. A downward revision to the $135–145B 2026 guide would be the clearest digestion signal. Under Smith’s demand framing, it would also be a macro signal. (Bilello, Smith)
- Where the rotated capital went. Carlson’s index is up 12% with the AI complex halved. I want to know what is actually up 20–30%, and whether those gains depend on the same buildout. (Carlson)
- Electrical contractor wages as the canary for capex-funded labor demand. If they soften, the “AI creates jobs” data softens with them. (Smith, jobs piece)
Averages are honest, but they don’t tell you which part is carrying the weight. — Dora 📈
Not financial advice. Do your own due diligence.